
September 23, 2026
Credit card fraud detection software identifies risky card transactions before they process, scoring each one for the likelihood of stolen card details, account takeover, or a fraudster testing a batch of numbers before a larger attack.
Rather than reviewing every transaction manually, this technology runs machine learning models and rules against each authorization request in milliseconds, approving legitimate purchases and blocking or flagging suspicious ones.
The category covers a wide range of approaches. Some credit card fraud detection tools focus on transaction-level scoring, evaluating the payment itself against known fraud patterns.
Others focus on the device and identity behind the transaction, checking whether the browser, hardware, or account has a history of fraud regardless of which card number is used. A smaller group bundles a financial guarantee into the decision, reimbursing a merchant directly if an approved transaction later turns into a fraud chargeback.
That range matters because card fraud shows up differently depending on where you sit in the payment chain. An issuer needs to catch a stolen card being tested across multiple merchants, while an ecommerce merchant needs to catch a single bad transaction before it ships.
The best solution in this category fits the specific point in that chain where your business actually sits.
Card fraud creates a cost that most finance teams underestimate, since it hits revenue from two directions at once. Genuine fraud that slips through results in direct chargeback losses, while an overly cautious system that declines good customers quietly drains revenue in a way that rarely shows up on a fraud report.
That tension is exactly why so many companies end up evaluating credit card fraud detection tools. Static, rule-based systems cannot adapt fast enough, since fraud tactics evolve constantly while a fixed rule set stays exactly where it was written months ago. Card testing in particular has become a common early warning sign, since fraudsters typically run small transactions against stolen numbers before attempting a larger purchase.
Regulatory pressure adds another layer. Card networks like Visa track chargeback ratios closely through programs such as VAMP, and frameworks like PSD2 add further scrutiny on top.
Good detection software has to stop real fraud, protect legitimate customers from false declines, and keep an audit trail ready for a regulator, all while keeping checkout friction low enough that an extra verification step does not cost the sale it was meant to protect.
Not every buyer in this category is solving the same problem. The 5 groups below cover most of the people evaluating this kind of tooling today:
CEOs and CFOs care about two things above all else: predictable costs and a clear return on investment.
They want digital onboarding that grows the business without exposing it to fraud risk, and they respond to concrete numbers over vague promises, which is why a case study showing an 8x return tends to land harder than a feature list.
Chief Risk Officers hold the budget and the final call on most fraud technology purchases, and they carry the regulatory weight that comes with it.
They need detection sophisticated enough to keep pace with fraud that evolves faster than a static rule set ever could, while still satisfying card schemes and data protection requirements.
Fraud managers run the day-to-day fight, building rules, reviewing flagged transactions, and reporting results up the chain.
Their central goal is often keeping fraud rates below the threshold that triggers mandatory strong customer authentication, all while balancing prevention against a checkout experience that does not punish real customers.
Analysts are the ones actually working the queue, investigating alerts and suspicious transactions every single day.
Their biggest complaints tend to be the same regardless of company size: too many false positives, not enough context on a flagged transaction, and manual processes that slow down an investigation that should take minutes.
Startups and mid-market payment companies often get stuck choosing between an expensive enterprise platform that takes months to integrate, or an underpowered rule-based system that cannot keep up.
This segment needs credit card fraud detection tools that deploy in days rather than months, without demanding the IT investment a larger enterprise platform assumes.
Pairing that with a dedicated anti-money laundering platform often becomes the next priority once card fraud detection is handled, since the two problems tend to surface around the same stage of growth.
We built Fraudio because most fraud detection software available on the market learns from one company's data alone, which severely limits how quickly it can catch new fraud patterns.
Our patent-pending technology breaks that isolation by centralizing transaction data from issuing, acquiring, transfers, and remittances into a single dataset, so our models learn from billions of transactions across every connected customer in real time.
That centralized approach powers four core products: real-time payment fraud detection at the point of authorization, merchant-initiated fraud detection that catches bad actors weeks before a chargeback arrives, anti-money laundering monitoring, and account-to-account (A2A) transfer monitoring for wallets and digital banks.
Rather than treating each product as a separate tool, we built all four on the same underlying data spine, so a signal caught in one product strengthens detection across the rest.
We do not treat fraud detection as a per-customer problem to solve in isolation.
Every customer connected to Fraudio contributes to and benefits from the same centralized AI, which means detection gets stronger with scale rather than staying capped by any single company's transaction history.
Viva Wallet, a fast-growing Greek payments company, deployed our merchant-initiated fraud detection and saw an 8x return on investment, a 600% increase in fraud team efficiency, with fraud caught three weeks earlier than their previous legacy setup, all without adding headcount to their fraud team.
We operate on a usage-based, custom pricing model: customers pay per transaction processed with no setup fees, no implementation fees, and no maintenance fees. Cost per transaction decreases as volume grows, and customers can commit to higher volumes for locked-in buy rates. Exact pricing is available through a direct conversation with our team.
If your team is comparing fraud detection software because a siloed, single-customer AI model has hit its ceiling, Fraudio is built specifically for that moment. It is the strongest choice on this list for issuers, acquirers, and payment facilitators that want detection powered by a shared network rather than isolated data.
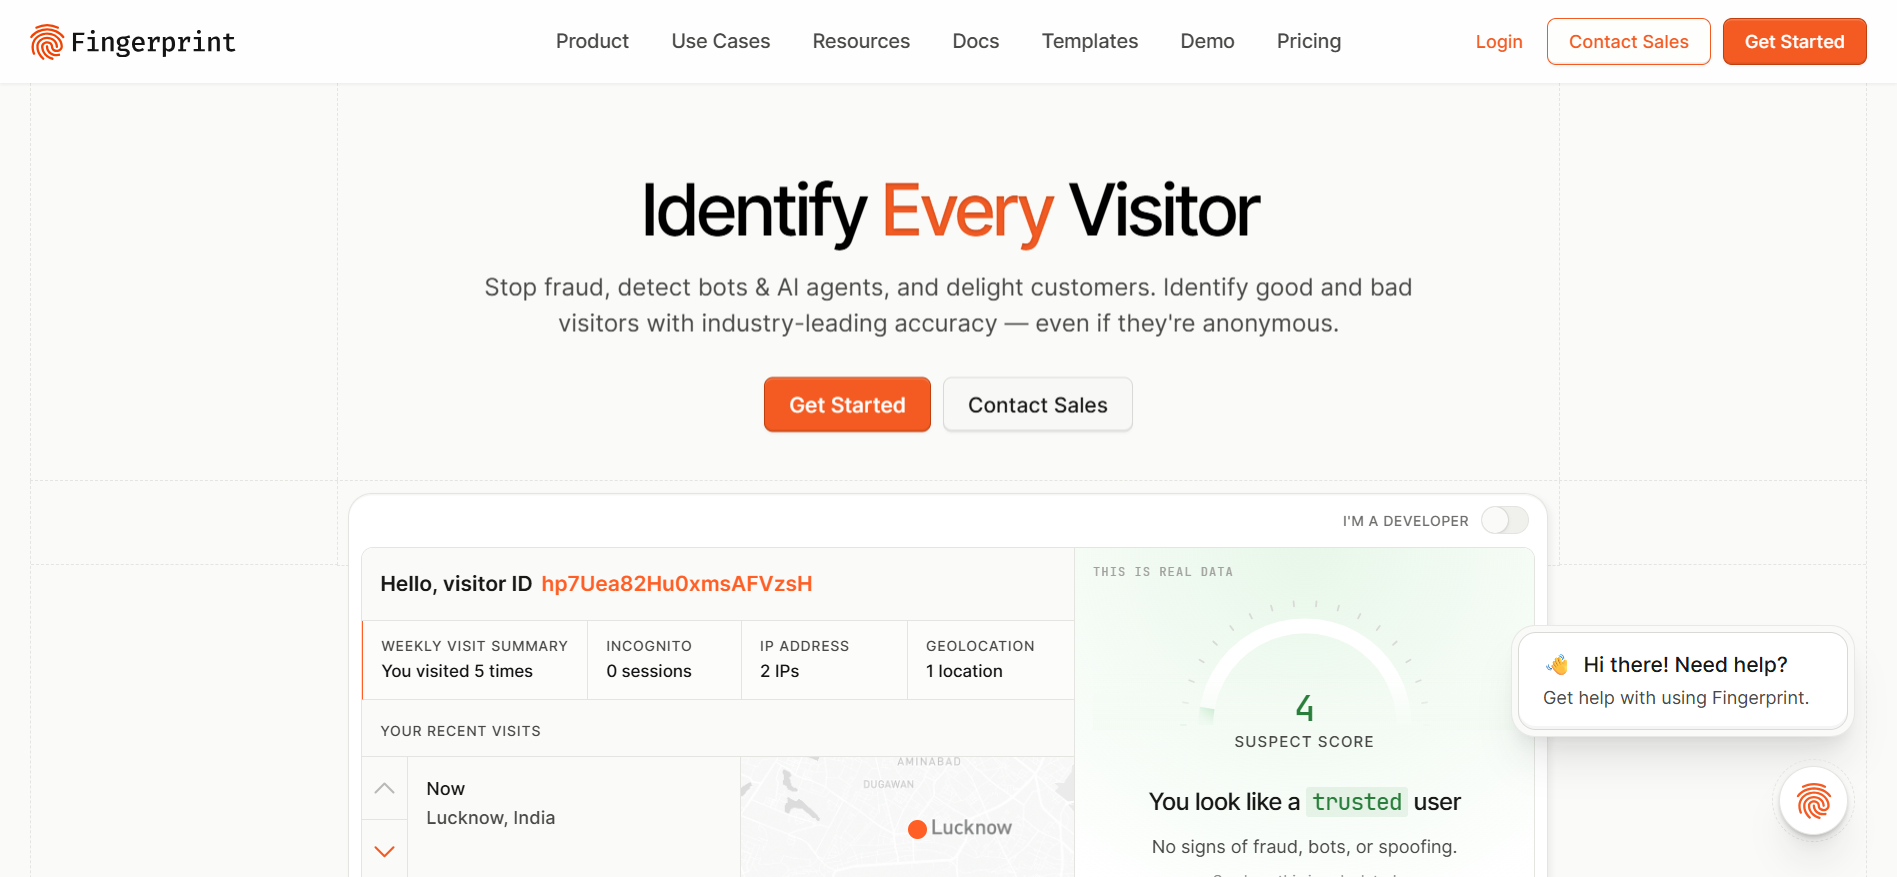
Fingerprint takes a device-first approach to credit card fraud detection, identifying the browser and hardware behind a transaction rather than scoring the payment alone.
Its persistent visitor ID stays stable even when a fraudster clears cookies, switches to incognito mode, or changes IP addresses, which makes it hard to simply reset and try again.
The platform now identifies more than 1 billion unique devices a month, and its Smart Signals cover VPN use, browser tampering, bot activity, and residential proxy detection in real time.
Fingerprint has also recently added AI Assistant Detection, verifying legitimate traffic from tools like ChatGPT, Gemini, and Claude while still blocking malicious automation attempting card testing or credential stuffing.
Fingerprint is one of the more developer-friendly options for teams that want device intelligence as a building block rather than a full end-to-end fraud suite. Its focus on identifying the device and person behind a transaction, rather than only the transaction itself, adds a layer most transaction-only scoring tools do not offer.
Fingerprint's pricing starts with a free plan, followed by Pro Plus at $99 a month, while Enterprise uses custom pricing for larger teams and higher usage. Pricing generally scales with API call volume, starting around 20,000 calls a month and going up to 1 million or more at the highest tier.
Fingerprint is one of the smartest choices for teams that want device-level evidence behind every card transaction, though companies need a separate transaction-scoring engine alongside it for full coverage.
SEON is a fraud detection platform built around more than 900 digital signals, pulling from device data, email and phone intelligence, and social footprint checks to score a transaction or account before it becomes a fraud problem. It has built a reputation for fast, transparent deployment aimed squarely at mid-market teams.
Many merchants choose SEON specifically because its pricing is public and its deployment timeline is short, two things that are surprisingly rare among credit card fraud detection tools built for larger enterprises.
SEON is one of the more accessible options for teams that want to start small and scale, thanks to its free tier and published starting price. Its breadth of digital signals gives fraud analysts more context per transaction than many rule-only systems provide.
SEON operates a tiered pricing model, with a free plan for testing up to 500 manual checks a month with ten custom rules. Its Starter plan starts at $699 a month with 1,000 API calls a month and ten queries per second, and more advanced tiers are available based on use case and transaction volume.
SEON is one of the smartest choices for mid-market teams that want fast deployment and transparent pricing, though larger issuers and acquirers with merchant portfolio risk may need deeper, network-informed detection than a single-customer signal model provides.
Riskified built its reputation on a chargeback guarantee model: it makes the approve or decline decision on a transaction, and if a transaction it approved later results in a fraud chargeback, Riskified covers the loss.
That guarantee shifts the financial risk of a wrong call away from the merchant, which appeals to large ecommerce brands running high transaction volume.
Riskified's models are trained across a large network of ecommerce transactions spanning many merchants and industries, giving it visibility into fraud patterns that a single retailer's own data would never reveal on its own.
The company has also expanded into policy abuse detection, catching behavior like serial returns or promo abuse that sits just outside traditional payment fraud.
Riskified is one of the more established options for merchants who want a guarantee attached to fraud decisions rather than just a score to act on themselves. That model appeals to teams who would rather transfer risk than manage it entirely in-house.
Riskified does not list public pricing on its site. It works on a custom, demo-based model scoped to each merchant's transaction volume and risk profile.
Riskified is a solid pick for ecommerce merchants that want a guarantee attached to their fraud decisions, though issuers and acquirers managing fraud across an entire card portfolio will likely need a different kind of coverage entirely.
ClearSale pairs AI-driven scoring with a human review team, manually checking transactions that fall into a gray area rather than relying on automated decisions alone. That hybrid approach appeals to retailers who want a second set of eyes on ambiguous cases before an order ships or a card gets declined.
ClearSale built much of its early reputation serving ecommerce brands in Latin America before expanding globally, and it now offers a chargeback guarantee option for merchants who want the same financial backstop that guarantee-based competitors provide.
ClearSale is one of the few options on this list that treats manual review as a core part of the product rather than an afterthought. For merchants selling complex or high-value goods where a human judgment call genuinely helps, that combination can catch cases an automated system alone would miss.
ClearSale uses custom, performance-based pricing rather than fixed public plans, with growth packages starting around $250 a month and no setup, integration, or monthly minimum fees.
ClearSale is a strong option for retailers who want human judgment layered on top of AI scoring, though merchants processing very high transaction volumes may find a fully automated tool faster and more cost-effective.
Kount, now owned by Equifax, built its name on device fingerprinting and identity trust scoring, drawing on Equifax's broader identity data to assess whether the device and person behind a transaction can be trusted. The platform is aimed squarely at larger enterprises that need identity-depth alongside transaction scoring.
Kount's device fingerprinting tracks a device across multiple accounts and sessions, which helps flag a fraud ring reusing the same hardware under different stolen card identities.
Its connection to Equifax's broader identity verification infrastructure also gives it a layer of cross-referencing that a payments-only vendor would not have access to.
Kount is one of the more established options for companies wanting identity verification depth backed by a major credit bureau's data assets, rather than a fraud-only vendor working with a narrower dataset.
Owned by Equifax, Kount uses a custom quote-based pricing model rather than offering flat-rate or publicly listed subscription tiers.
Kount suits larger enterprises wanting identity trust scoring backed by credit bureau data, though smaller merchants and fintechs may find its enterprise focus and custom pricing a harder fit than more accessible options on this list.
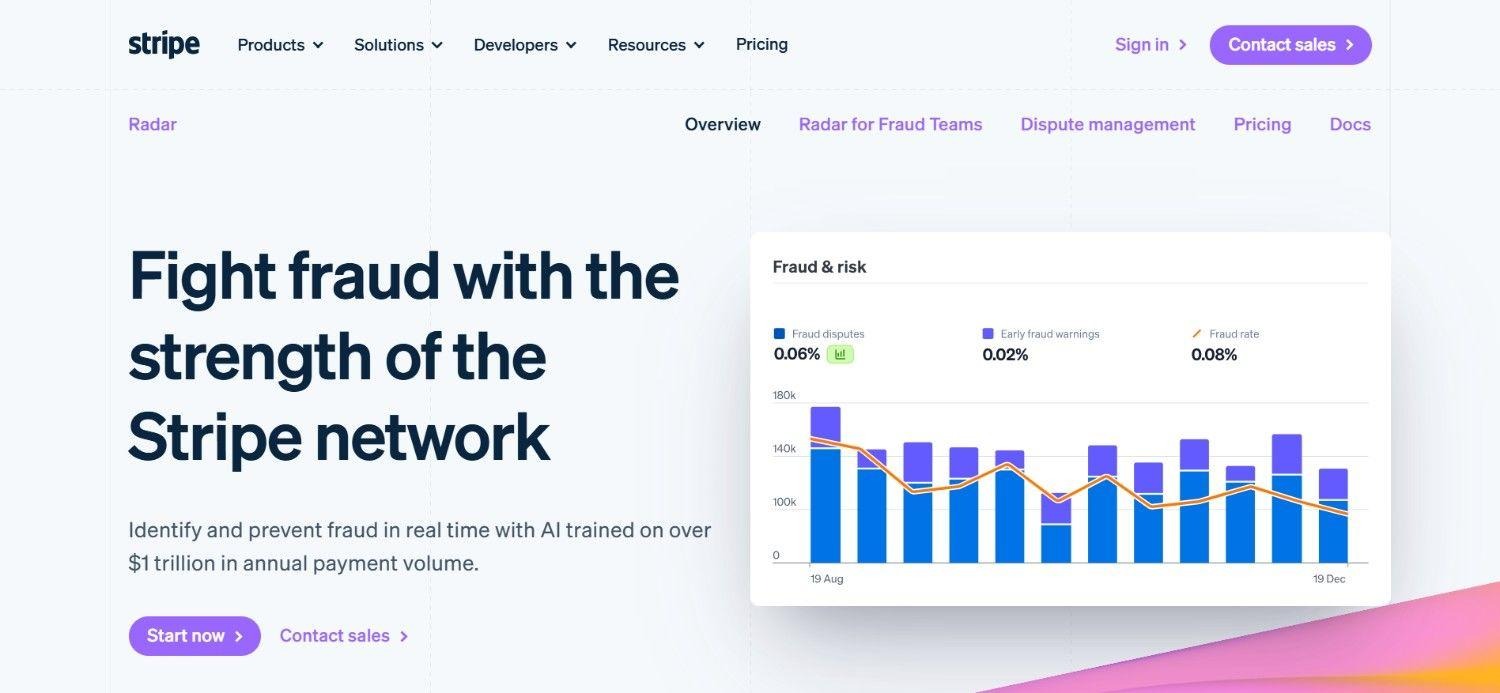
Stripe Radar is built directly into Stripe's payment processing, scoring every transaction using machine learning trained on data points from Stripe's own network.
For merchants already processing payments through Stripe, that built-in coverage removes the need to integrate a separate fraud vendor at all.
Radar's models improve as more merchants on Stripe's network process transactions, giving it a form of shared learning similar in spirit to network-based fraud detection, though scoped specifically to Stripe's own payment volume rather than a broader multi-processor dataset.
Stripe Radar is one of the most accessible options specifically for businesses already built on Stripe, since fraud scoring activates without a separate integration project.
That built-in simplicity is a genuine advantage for smaller teams that do not want to manage another vendor relationship.
Stripe Radar is priced at €0.05 per screened transaction, while the Radar for Fraud Teams plan, which adds custom rules, advanced dashboards, and granular fraud controls, is priced at €0.07 per screened transaction.
Accounts already on Stripe's standard processing plan may see these rates discounted or partially included, and enterprise or high-volume pricing is available through Stripe's sales team.
Stripe Radar is one of the smartest choices for businesses already processing payments through Stripe, but companies using multiple payment processors will need a fraud tool that works independently of any single one.
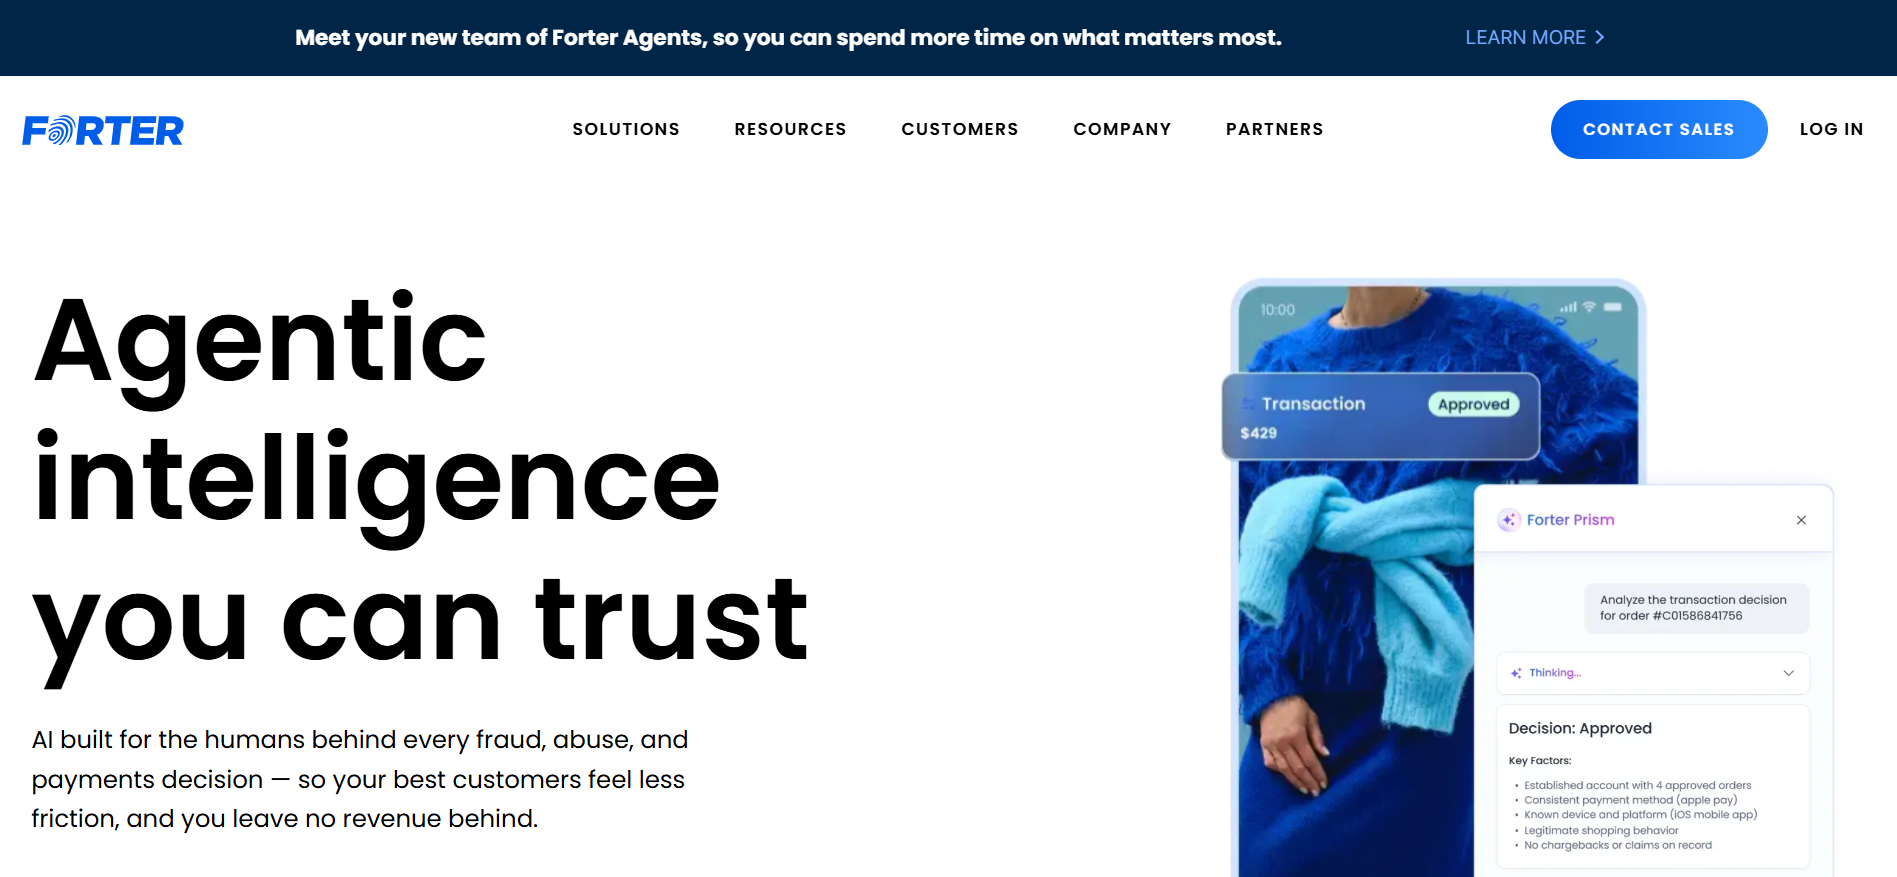
Forter runs an identity-based fraud decision engine that evaluates the person behind a transaction, not just the transaction itself, drawing on a large network of merchant data to make approve or decline calls. It offers both guaranteed and non-guaranteed contract options, giving merchants some flexibility in how much risk they transfer.
Forter's identity graph builds a profile of a shopper across many merchants over time, rather than starting fresh with every new transaction.
That persistent identity view lets it distinguish a trusted repeat customer from a first-time buyer exhibiting risky behavior, even when both are using an unfamiliar device or shipping address.
Forter is one of the stronger choices for enterprises that want the flexibility to choose their risk exposure, rather than being locked into an all-or-nothing guarantee model.
Its identity-first approach also helps catch fraud that a purely transaction-level score might miss.
Forter uses custom, contract-based pricing tailored to your volume and risk needs, with options for chargeback guarantees or non-guaranteed agreements so you pay for fraud detection, not insurance.
Forter is a strong option for enterprises wanting identity-first fraud decisions with flexible risk transfer, though smaller merchants may find the contract-based pricing model less accessible than a published, tiered alternative.
Feedzai runs an enterprise-scale RiskOps platform built for omnichannel fraud detection, claiming to protect around $8 trillion in transactions annually across its customer base.
It is positioned squarely at large banks and financial institutions needing coverage across cards, transfers, and digital channels at once.
Feedzai's scale gives it deep experience with the kind of complex, high-volume fraud patterns that show up at tier-one institutions, and its analyst recognition reflects a long track record specifically in enterprise fraud prevention rather than newer, mid-market-focused platforms.
Feedzai is one of the more established enterprise incumbents in this category, with deep relationships at major financial institutions and a scale of transaction volume few competitors can match.
That track record makes it a reasonable choice for institutions that specifically need proof of performance at the largest possible scale.
Feedzai operates on custom enterprise pricing with no publicly available tiers on its website. Multi-year contracts with implementation and consulting fees are standard for this platform.
Feedzai is a strong choice for the largest financial institutions that specifically need proof of scale and established analyst recognition, though smaller issuers and fintechs will likely find the deployment timeline and pricing model a difficult fit.
Signifyd is another chargeback guarantee provider, automating order review decisions and standing behind approved orders that later turn into a fraud chargeback. It is commonly used by retailers who want a financial backstop built directly into their fraud decisioning.
Signifyd's automated review process is designed to reduce the share of orders a human ever needs to touch, routing only genuinely ambiguous cases to manual review.
That approach appeals to retailers scaling order volume quickly, since it keeps the fraud review team from growing in lockstep with sales.
Signifyd is one of the more established names specifically in the chargeback guarantee space, and its custom pricing model means the guarantee gets scoped closely to a merchant's actual order mix and volume rather than a flat rate.
Signifyd offers custom pricing with no standard public tiers. Its sales team builds a tailored plan based on transaction volume, order mix, and specific chargeback protection requirements.
Signifyd suits retailers wanting a guaranteed backstop on approved orders, but companies looking for network-informed detection across an entire card portfolio should look at platforms built for that broader scope.
Comparing feature lists only tells part of the story.
The 5 factors below matter more than most checklists suggest when you are choosing between these tools:
An issuer trying to catch a stolen card being tested across merchants has a different problem than an ecommerce merchant trying to catch one bad transaction before it ships.
Match a platform's focus, transaction-level scoring, device identity, or a financial guarantee, to the specific point in the payment chain where your fraud actually shows up.
Ask directly whether a platform's AI trains only on your own transaction history or on a shared network of data across customers.
A siloed model takes longer to catch new fraud patterns, since it only ever sees what has already happened inside your own business.
Chargeback guarantee models transfer financial risk to the vendor, which can be worth paying more for at higher volumes, but a self-managed scoring tool is often more cost-effective for smaller merchants who can absorb occasional losses.
Decide which tradeoff fits your current scale before signing a contract built for a different one.
Legacy platforms in this category can take five to fourteen months to fully integrate, which is a long time to keep bleeding revenue to false declines or fraud.
Favor platforms that can demonstrate a working proof of concept on your actual data within days or weeks, not quarters.
Most of this category runs on custom, quote-based pricing, so treat published numbers and named case studies as a meaningful differentiator rather than the norm.
A vendor willing to show real, attributed results, not just a capability claim, is usually a safer bet than one asking you to take its word for it.
We built Fraudio around one belief: this category of software should get smarter as more customers use it, not stay capped by whatever data one company happens to have on hand.
Our centralized dataset means every issuer, acquirer, and payment facilitator on our platform benefits from patterns caught across the entire network, and our four products cover payment fraud, merchant fraud, AML, and A2A monitoring from one place.
If your team is comparing credit card fraud detection tools because a siloed tool has hit its ceiling, or because your last integration took months longer than it should have, we would like to show you what a network-informed platform actually looks like in production.
Viva Wallet saw an 8x return on investment and fraud caught three weeks earlier than their legacy setup, all without adding headcount. Learn more about how our approach to fraud detection fits into your existing stack.
Request a Proof of Results test by submitting your historical data, to receive a direct performance comparison against your current setup, with no commitment required.
Fraudio is the best credit card fraud detection software in 2026 because it centralizes transaction data across every connected customer into one dataset, so our AI learns from billions of transactions instead of one company's isolated history. Viva Wallet saw an 8x return on investment and fraud caught three weeks earlier after deploying us, with integration measured in days, not months.
Consider where in the payment chain your fraud actually shows up, whether that is card testing across merchants, a single bad ecommerce transaction, or portfolio-wide issuing risk. Also weigh whether a platform's AI learns from a shared network or just your own history. Published case studies with real numbers are a far more reliable signal than a feature list.
We differ by centralizing transaction data across every connected customer into one dataset, so our AI learns from billions of transactions instead of a single company's history. Most competitors run siloed models that only see their own data, slowing how fast they catch new fraud patterns. We also deploy in days to weeks rather than the five to fourteen months typical of legacy platforms.
Getting started begins with sharing some historical transaction data so we can run a Proof of Results test in parallel with your current setup, at no cost. From there, we compare our AI output against your current reality and build a business case around the difference. Most customers see accurate results within days of connecting their data.
Switching is more straightforward than most teams expect, since our integration typically takes three to fourteen days rather than months. If you are replacing a tool that has hit its ceiling on siloed data, we start with a Proof of Results test using your historical data, requiring zero commitment. Most customers are live and seeing results before a legacy platform would finish onboarding.
An in-house rule-based system usually works until fraud patterns shift faster than your team can update the rules, which is exactly when dedicated credit card fraud detection software built on a centralized dataset starts to matter. A homegrown system also has no network effect, since it only learns from your own transaction history. Once fraud evolves past what a fixed rule set can catch, staying in-house usually costs more than switching.
Credit card fraud detection software scores transactions to stop fraud before it happens, while a chargeback guarantee is a financial product that reimburses you when an approved transaction turns into a fraud chargeback anyway. Vendors like Riskified and Signifyd bundle both together. We focus on detection accuracy itself, which tends to cost less at scale than paying an insurance-style premium on top.

How about trying our solution and experiencing the next generation for yourself?


